Get In-Demand Finance Certifications
A simple, unincorporated business entity owned by one individual
A sole proprietorship is an unincorporated business owned and run by one person, with no legal separation between the owner and the business. The owner keeps all profits and reports them on their personal tax return but is personally liable for all business debts. It is the simplest and cheapest business structure to start.
It is also known as individual entrepreneurship, sole trader, or simply proprietorship.
The business owner, also known as a proprietor or a trader, conducts business using their legal name. They may also choose to do business using another name by registering a trade name with their local authority.
This type of business is the easiest and cheapest form to start. For this reason, it is common among small businesses, freelancers, and other self-employed individuals.
A sole proprietorship begins and ends when the business owner decides, or upon their death.
A sole proprietorship may transform into another, more complex business structure if the business grows substantially.
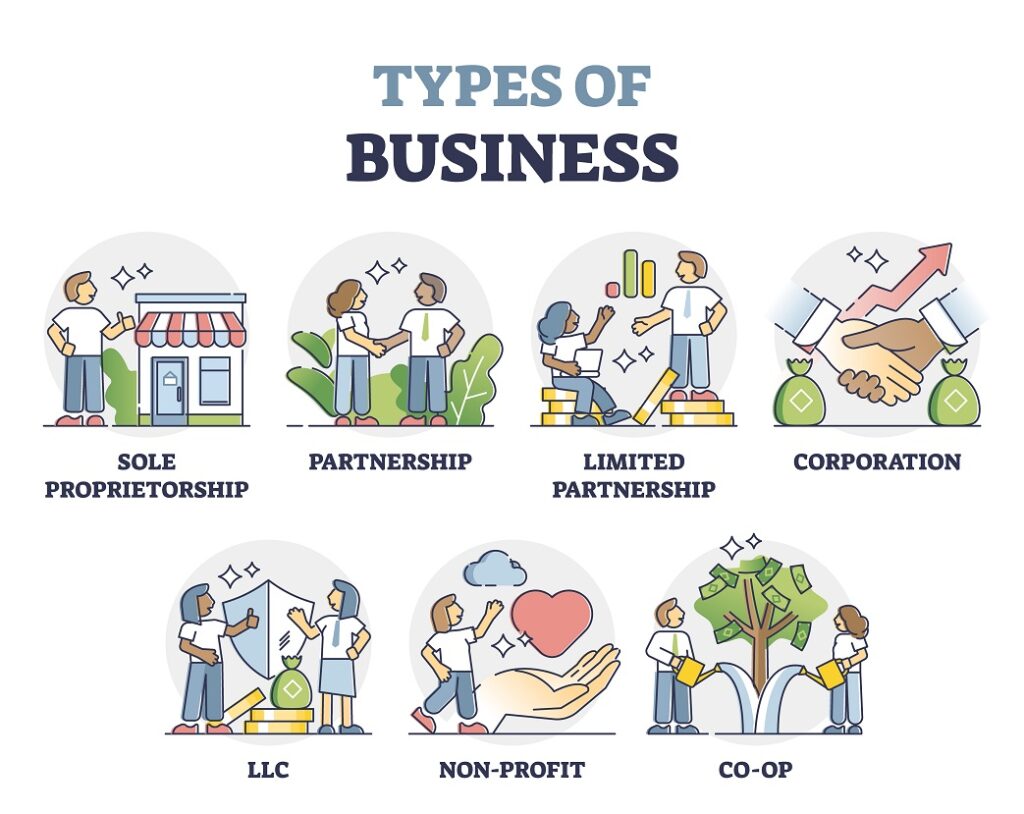
Though the process varies depending on the jurisdiction, establishing a sole proprietorship is generally an easy and inexpensive process, unlike forming a partnership or a corporation[1].
Compared to other business forms, there is very little paperwork a proprietor needs to file with their local authorities. As a result, proprietors do not have to wait long before they have permission to carry on a business.
The start-up fees are also low, in line with many government policies that encourage entrepreneurs to take risks and grow the economy by minimizing the friction of starting new businesses.
There are very few government rules and regulations that are specific to proprietors. Sole proprietors must keep proper records, file, and pay taxes on the business income and other personal income sources.
Record keeping and tax filing obligations are generally no more complicated than maintaining records for individual tax filings. Due to the time and the effort, proprietors may wish to pay for specialized software and advisors to streamline the time spent on administration.
Government rules for larger enterprises and public companies, such as financial disclosure, require far more administration and do not apply to sole proprietorships.
Proprietors control all aspects of their business, including production, sales, finance, personnel, etc. This degree of freedom is attractive to many entrepreneurs, as the venture’s success also means personal success.
To be successful, proprietors must be “good enough” at the various aspects of their business they have control over.
While some proprietors have employees and delegate some of their authority, they are ultimately accountable for all the decisions and acts of their business.
There is no legal separation between the owner and the business, so the owner gets 100% of the profits. Although all profits go to the owner, taxes are paid once, and proprietors pay taxes individually.
Proprietors must pay individual taxes on the income periodically, for example, as part of the annual individual tax filing. Tax payments may be more frequent, for example, quarterly, depending on local tax rules.
Making regular payments can help a proprietor keep their tax burden from becoming overwhelming and incurring tax penalties. Tax advisors can help proprietors estimate taxes so they can set aside enough of the profits to make mandatory government payments[2].
There is no legal separation between the owner and the business. Similar to how all profits flow to the owner, all debts and obligations rest with the proprietor.
If the business cannot satisfy its obligations, creditors may pursue the proprietor’s personal assets in order to be repaid.
This accountability is clearly outlined within legal documents signed with lenders, sometimes called a promissory note. A proprietor does not need to provide a personal guarantee to their sole proprietorship, as the two are the same legal entity in the eyes of the law.
Owners put their own resources to bear when going into business for themselves. There are limits to their financial resources and the amount of credit they get when they seek out lending relationships.
Proprietors cannot sell shares, or interest, in their business to raise money.
Putting ideas into reality is risky and can be costly. Keeping a business going can be capital intensive. Some expenses must be incurred before revenue is generated. Any sales on credit, and any cash paid towards expenses, must be financed by working capital. Equipment and other long-use resources required for the business must be rented or financed.
If business requirements exceed the resources and financing available to proprietors, they will need to closely manage their working capital and potentially curtail the acquisition of fixed assets.
A fulsome business plan helps proprietors determine the capital necessary to start up, sustain, and grow the business.
If the owner cannot or does not want to operate the business, it stops. An owner may have a family member or trusted employee who can briefly work in place of the owner in the case of illness or any temporary and unforeseen reason.
Business interruption insurance may cover expenses for longer-term issues, but these policies cannot complete the work that a proprietor has already taken on.
Without a separate legal identity, sole proprietorships cannot readily pass any intangible assets from one owner to another. Aside from equipment and fixed assets, the value of the business is inherently tied to the proprietor.
To make any sale attractive, a proprietor must find someone with comparable skills willing to purchase the goodwill the owner has built up. If they cannot find a buyer, the proprietor may pass the business on to a family member or a trusted employee if one exists.
The proprietor must make “good enough” decisions in all business areas. If an owner does not have enough knowledge or skills, their decisions may be flawed. There is a finite amount of time to do things correctly or learn to do everything adequately.
It can be difficult for individuals to manage all aspects of their business properly. The owner can hire employees, outside help, or get professional advice on parts of the business process.
The owner’s ability to use their own time to earn greater profits to offset the cost of hiring help is a crucial consideration.
Employees, contractors, and other services may be too costly for such sole proprietorships. The owner’s time must be productive enough to pay for the cost of hiring others.
Many sole proprietors eventually hire help, and managing people becomes part of running the business. This guide to essential management skills covers delegation, communication, and planning for new managers.
The main difference is liability. A sole proprietor is personally responsible for every business debt, while a limited liability company (LLC) is a separate legal entity that generally shields the owner’s personal assets. An LLC costs more to set up and maintain because it must be registered with the state, but a single-member LLC is taxed the same way as a sole proprietorship by default.
| Sole Proprietorship | Single-Member LLC | |
|---|---|---|
| Owner Liability | Unlimited, personal | Generally limited to the business |
| Setup | No state filing (a trade name registration may apply) | State registration and annual fees |
| Default US Tax Treatment | Profit reported on owner's return (Schedule C) | Same as a sole proprietorship unless it elects otherwise |
| Raising Capital | Owner's funds and loans only | Can add members |
A sole proprietorship doesn’t pay tax separately. The owner reports business profit or loss on Schedule C with their Form 1040 and pays self-employment tax on Schedule SE, which covers Social Security and Medicare at a combined 15.3%. Because no employer withholds tax, most sole proprietors make quarterly estimated payments using Form 1040-ES.
Many small and service businesses start as sole proprietorships, including:
As a sole proprietor, you handle the books, the cash flow, and the planning yourself. This guide to the best online professional development courses compares flexible options for building those skills alongside running a business.
See all Management & Strategy resources
You are a sole proprietor if you run an unincorporated business on your own and haven’t registered it as an LLC or corporation. In the US, you become one automatically when you start doing business for yourself.
Not always. A sole proprietor needs an EIN if they have employees, file employment, excise, or alcohol, tobacco and firearms tax returns, or have a Keogh plan. Without any of those, many sole proprietors use their Social Security number on business tax filings.
The four common structures are sole proprietorship, partnership, limited liability company (LLC), and corporation. They differ in ownership, owner liability, taxation, and how easily they can raise capital.