Get Certified for Financial Modeling (FMVA)®
Gain in-demand industry knowledge and hands-on practice that will help you stand out from the competition and become a world-class financial analyst.
An increase or decease in money over a period of time
Cash Flow (CF) is the increase or decrease in the amount of money a business, institution, or individual has. In finance, the term is used to describe the amount of cash (currency) that is generated or consumed in a given time period. There are many types of CF, with various important uses for running a business and performing financial analysis. This guide will explore all of them in detail.
There are three primary types of cash flow, each corresponding to a section of the cash flow statement:
Operating cash flow (OCF) is the cash generated or consumed by a company’s core business activities, collecting payments from customers, paying suppliers, meeting payroll, and covering other day-to-day expenses. It is the first section of the cash flow statement and is often the most important indicator of financial health. A business that consistently generates positive operating cash flow can fund growth without relying on external financing.
Investing cash flow reflects cash spent on or received from long-term assets and investments. Common outflows include purchases of equipment, property, or securities; common inflows include the sale of those assets or proceeds from divestitures. Negative investing cash flow is not necessarily a warning sign, it often reflects productive capital spending.
Financing cash flow tracks cash exchanged with lenders and shareholders. Inflows include new borrowings and stock issuances; outflows include loan repayments, share buybacks, and dividend payments. The financing section shows how a company funds itself and returns capital to investors.
Beyond the three statement categories, finance professionals use several derived metrics for valuation and analysis:
For a detailed comparison of these advanced metrics, see the Cash Flow Metrics guide.
The net cash flow for a period is the sum of its three components:
Net Cash Flow = Operating Cash Flow + Investing Cash Flow + Financing Cash Flow
A positive result means more cash came in than went out; a negative result means the business spent or distributed more cash than it received.
Most companies calculate operating cash flow using the indirect method, which starts with net income and adjusts for non-cash items and changes in working capital:
Start with Net Income, then adjust:
Free cash flow strips out the investment required to maintain the business:
FCF = Operating Cash Flow − Capital Expenditures
A positive FCF means the business generates surplus cash after maintaining its assets, that cash can fund acquisitions, pay down debt, or be returned to shareholders.
Consider a small manufacturer over one quarter:
| Cash Flow Category | Amount |
|---|---|
| Collected from customers (operating inflow) | +$4,500,000 |
| Paid in operating expenses - wages, materials, rent (outflow) | −$3,200,000 |
| Net Operating Cash Flow | +$1,300,000 |
| Equipment purchase (investing outflow) | −$400,000 |
| Net Investing Cash Flow | −$400,000 |
| New bank loan received (financing inflow) | +$500,000 |
| Net Financing Cash Flow | +$500,000 |
| Net Cash Flow for the Quarter | +$1,400,000 |
Note that the company reported $900,000 in net income on its income statement for the same period, $500,000 less than its operating cash flow. The gap arises because the income statement recognized revenue before all invoices were collected and because depreciation on the new equipment reduced income without reducing cash.
This difference between income and cash flow is why analysts always read the cash flow statement alongside the income statement.
Cash Flow has many uses in both operating a business and in performing financial analysis. In fact, it’s one of the most important metrics in all of finance and accounting.
The most common cash metrics and uses of CF are the following:
Cash flow and net income often diverge, and understanding why is one of the most important skills in financial analysis.
Net income is calculated under accrual accounting: revenue is recognized when earned (not when cash is received), and expenses are matched to the period they relate to (not when cash is paid). This means a company can report high net income while simultaneously burning through cash.
Common reasons for a cash-income gap:
A company can be profitable on paper while experiencing negative cash flow, and conversely, a company with modest net income may generate very strong cash flow. Cash flow analysis cuts through accrual-accounting distortions to show what is actually moving through the business.
Since CF matters so much, it’s only natural that managers of businesses do everything in their power to increase it. In the section below, let’s explore how operators of businesses can try to increase the flow of cash in a company. Below is an infographic that demonstrates how CF can be increased using different strategies.
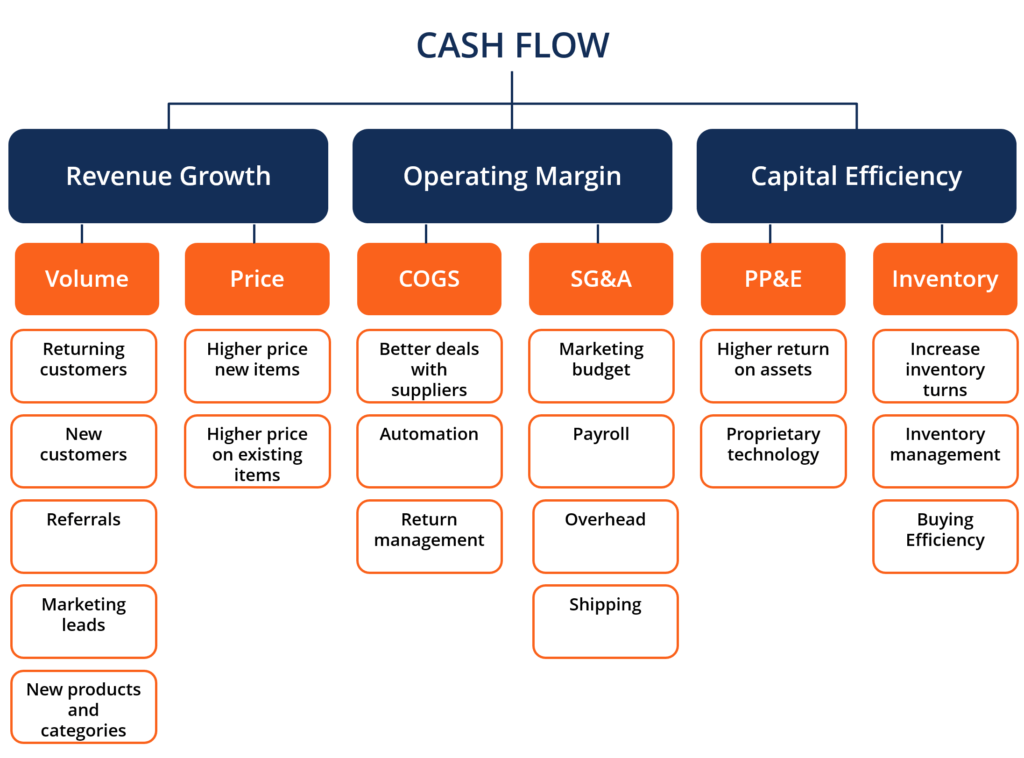
Managers of a business can increase CF using any of the levers listed above. The strategies for improving CF fall into one of three categories: revenue growth, operating margins, and capital efficiency. Each of those can then be broken down into higher volume, higher prices, lower cost of goods sold, lower SG&A, more efficient property, plant & equipment (PP&E), and more efficient inventory management.
Cash flow analysis sits at the core of nearly every financial model. Whether you are building a discounted cash flow (DCF) valuation, evaluating a company’s liquidity, or assessing the quality of reported earnings, your ability to identify and interpret operating, investing, and financing cash flows will determine the quality of your work.
For finance professionals in investment banking, private equity, and corporate FP&A, cash flow is not just a line on a statement — it is the primary lens through which business performance is judged. Understanding how to move from net income to free cash flow, how to spot working capital traps, and how to compare cash flow metrics across periods and peers separates analysts who add insight from those who report numbers.
The Financial Modeling & Valuation Analyst (FMVA®) certification from CFI covers cash flow analysis in depth, including hands-on practice building cash flow statements, DCF models, and free cash flow forecasts used in real-world transactions.
Thank you for reading CFI’s guide to Cash Flow. To keep learning and developing your knowledge of financial analysis, we highly recommend the additional CFI resources below: